   | |||
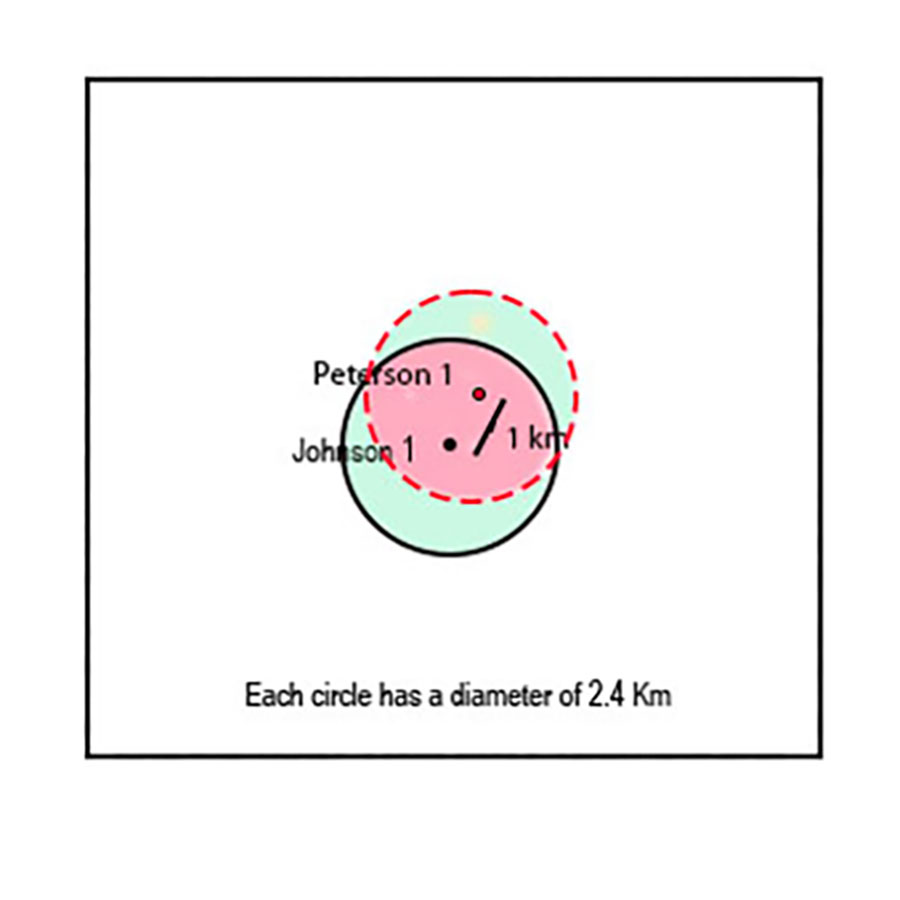
Sage Potash was Big, now GiantBob Moriarty I have a giant advantage over many of the financial commentators covering the junior resource markets. For about twenty years I spent 2-3 weeks a month traveling to different projects all over the world. Barb was quite happy to have me out of her hair so I got to see almost every sort of resource properties. I never counted how many sites I visited but it had to be in the 400-500 range. The mining business is interesting because the level of education is higher than any other field, I know of. Everybody seems to have at least a Bachelor’s degree with many Master’s degrees and a surprising number of Doctorates. When I was a systems programmer in computers a lot of years ago, I ran into a similar percentage of very bright people but they were almost all self-taught as I was. Computer programmers do not share their knowledge but geologists love teaching what they know and theorize. So, I learned a lot. That gives me a leg up because if you haven’t been to a whole lot of projects, there are simple issues you would have not experienced. Once I went to a big coal project in China with a 43-101 that was 100% Measured. I’d never seen that before, nor have I seen one since. But it was coal and that is why. When you have a flat project with similar grade in many holes, the QP can change the requirement for each of the three classifications. Measured, the highest, indicated, lower than measured but higher than inferred, and inferred, the lowest category. In the case of the Chinese resource, I seem to recall they could drill holes on a 500 or 1 km center. So, it didn’t take a lot of holes to generate resources into the measured category. Potash is the same. Sage Potash (SAGE-V) has a deposit in a large basin where it was once a large lake. Salt and other minerals flowed into the lake and settled at the bottom. Sage demonstrated this quality recently when they announced their 2nd drill hole resource on October 19th, 2026. If you go to page 3 of that press release you can see the new incredible resource of 771.5 million metric tonnes. And just below that table you can see how the QP justified the numbers. For the Measured Resource, he used a radius of influence of 0-750 metres. For the Indicated Resource he used a radius of influence of 750-2,000 meters and for the Inferred Resource he used a radius of influence of 2,000-4,000 meters. Drilling the 2nd hole has taken the 43-101 Resource from 298 million tonnes in the Inferred category to 771.5 million tonnes total. That’s a 259% increase in total resource with the higher regarded M&I resource showing a total of 226.1 million tonnes. In addition, the grade is one of the highest grade potash deposits in the world at over 40%. (Click on image to enlarge)
Based on only the first hole, Sage delivered a PEA in September of 2025. It showed an after-tax NPV of $502 million. If you use the same guess but increase the 43-101 resource by 259% by all rights you should increase the new NPV when it is completed to $1.3 billion. For a company with a $20 million market cap, that seems absurdly cheap to me. On the 19th when the new resource came out, the market was flooded with cheap shares that took the price down from $.115 to a low of $.09 on volume of over 2.6 million. Since there was an almost complete change of management in the past year over internal affairs, I suspect that a lot of former employees with a chip on their shoulder dumped their cheaply bought shares just to send a message. This stock was $.50 a share just over a year ago with only one hole complete. Frankly I thought the stunning new 43-101 number would double the price of the stock. Instead, it went down 25% and that makes no sense at all. Few people know this but the US only produces a tiny amount of potash, most is imported from Canada. “On March 20, 2025, President Trump declared potash a “critical mineral” and called for an increase in domestic production to reduce import dependence and strengthen national security (EO 14241)” I see two potential paths forward from here. First of all, readers need to be aware that this is actually a giant project. But giant projects require a lot of money to get into production. The US government appears to want to get involved in mining either directly or indirectly. They could fund this project to production. Alternatively, potash is not a commodity freely traded in any open market. There are only a few really big and powerful companies who control the potash marketplace today. I will guarantee they are watching Sage carefully. The resource they have already outlined represents many years of production and many billions in revenue. Any of them could come in and buy the entire company at a big premium and everyone would walk away happy. Meanwhile the company is working to further advance the project and at some point, will produce a pre-feasibility study. When they do, the shares will fly. I have bought a fair number of shares in the open market prior to this news. When I saw the fools dumping shares yesterday and today, I bought more. Sage is an advertiser. Naturally I am biased so do your own due diligence. Their only problem is a lack of visibility. Sage Potash Corp ### Bob Moriarty 321gold Ltd |



Copyright ©2001-2026 321gold Ltd. All Rights Reserved