|
|||
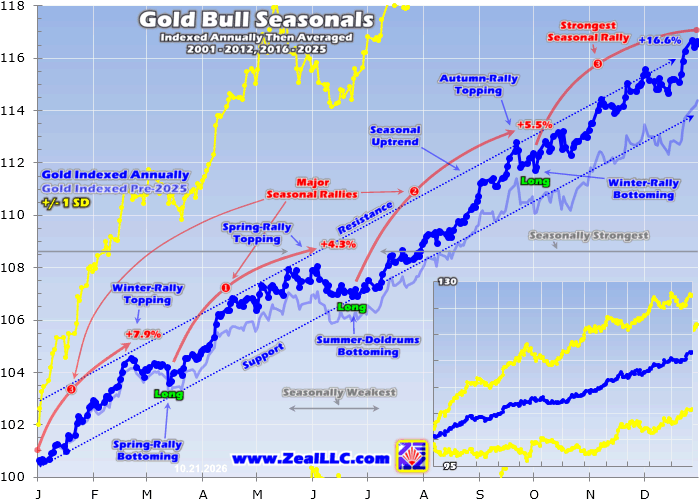
Gold Stocks' Winter Rally '26Adam Hamilton Gold stocks have been on a wild roller-coaster ride this year, soaring and plunging. Recent months have seen another round of the latter, with the miners sucked into gold's correction. That's been fueled by a mini-mania in Fed-rate-hike expectations and the resulting surging US dollar. All that gold and gold-stock selling has left technicals oversold and sentiment bearish, a great setup heading into their strong winter rally. Seasonality is the tendency for prices to exhibit recurring patterns at certain times during the calendar year. While seasonality doesn't drive price action, it quantifies annually-repeating behaviors driven by sentiment, technicals, and fundamentals. We humans are creatures of habit and herd, which naturally colors our trading decisions. The calendar year's passage affects the timing and intensity of buying and selling. Gold stocks display strong seasonality because their price action amplifies that of their dominant primary driver, gold. Gold's seasonality generally isn't driven by supply fluctuations like grown commodities see, as its mined supply remains relatively steady year-round. Instead gold's major seasonality is demand-driven, with global investment demand varying considerably depending on the time in the calendar year. This gold seasonality is fueled by well-known income-cycle and cultural drivers of outsized gold demand from around the world. Gold's biggest seasonal surge of all is just getting underway heading into winter. As the Indian-wedding-season gold-jewelry buying that normally drives this metal's big autumn rally winds down, the Western holiday season ramps up. The holiday spirit puts everyone in the mood to spend money. Men splurge on vast amounts of gold jewelry for Christmas gifts for their wives, girlfriends, and daughters. The holidays are also a major engagement season, with Christmas Eve and New Year's Eve being two of the biggest proposal nights of the year. Something like a third to half of the entire annual sales of many jewelry retailers come in November and December! And jewelry historically dominates overall gold demand. The World Gold Council closely tracks global gold supply and demand, publishing the latest data each quarter. During the last five calendar years, jewelry demand averaged 42% of overall total world gold demand! That is much larger than investment demand, which averaged 26% during that same 2021-to-2025 span. And that even includes the recent investment-heavy years of gold's late monster record bull. The usual frenzied Western jewelry buying heading into Christmas shifts to pure investment demand after year-end. That's when Western investors figure out how much surplus income they earned during the prior year after bonuses and taxes. Some of this is plowed into gold in January, driving it higher. Finally gold's big winter rally climaxes in late February on major Chinese New Year gold buying flaring up in Asia. So during its bull-market years, gold has usually tended to enjoy powerful winter rallies driven by these sequential episodes of outsized demand. Naturally the gold stocks follow gold higher, amplifying its gains due to their excellent profits leverage to the gold price. Today gold stocks are now once again early on in gold's strongest seasonal rally of the year, driven by this annually-recurring robust winter gold demand. Since it is gold's own demand-driven seasonality that fuels gold stocks' seasonality, that's logically the best place to start to understand what's likely coming. This old research thread focuses on modern bull-market seasonality, as bull and bear price action are quite different. Over the past quarter-century or so, gold enjoyed bull years in 2001 to 2012 then again from 2016 to 2025. Intervening bear years ran 2013 to 2015. In past gold-stock-seasonality essays I've analyzed all those many gold years, but their accumulation is making that space-prohibitive. Now fully 22 of these last 25 years qualify as gold-bull ones, and thus are included in this analysis. Naturally prevailing gold prices varied wildly across that long secular span, from just $257 in early April 2001 to a lofty $5,394 in late January 2026! So gold's raw price data sure isn't comparable. The vast range of gold levels spread over all those many years has to first be rendered in like-percentage terms in order to make them perfectly comparable with each other. Then they can be averaged together to distill out gold's bull-market seasonality. That's accomplished by individually indexing each calendar year's gold price action to its final close of the preceding year, which is recast at a common indexed baseline. I've always used 100 which makes subsequent gains easy to parse. From that, all gold action of the following year is recalculated which normalizes all years to the same simple scale. For example gold trading at 110 simply means it has rallied 10% from the prior year's close. Gold's current seasonality from 2001 to 2012 and 2016 to 2025 is rendered in dark-blue, with its prior year's pre-2025 data in light-blue.
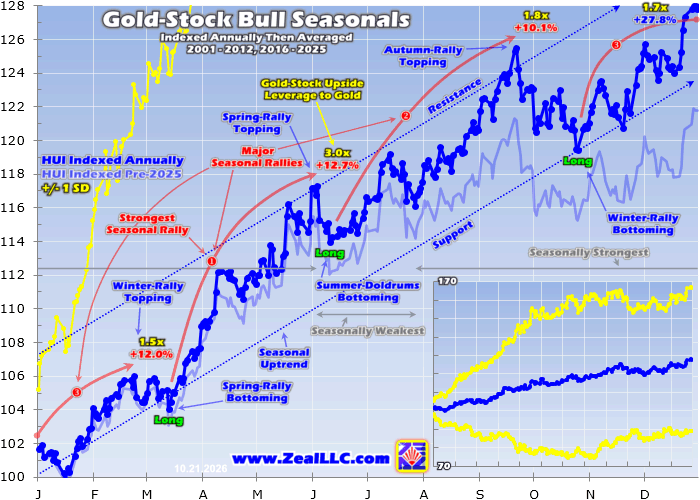
Across all these modern gold-bull years, gold has averaged fantastic 16.6% annual gains! With a stellar track record like that over 22 of these last 25 years, gold certainly deserves way more popularity with investors. Gold's strong and persistent gains across this past quarter-century are concentrated in its autumn, winter, and spring seasonal rallies, which respectively averaged an impressive 5.5%, 7.9%, and 4.3%. Gold's winter rally generally running from early October to late February is the strongest by far of these three seasonal rallies. Those 7.9% average gains across all modern gold-bull years are amazing, and include gold's two strongest calendar months seasonally. Gold has averaged 2.8% gains in January over this long secular span, and 2.0% gains in November. And gold's overall winter-rally gains can grow huge. Last year's is a great case in point. From early October 2025 to late January 2026, gold skyrocketed an astounding 39.9% in the terminal ascent of its late monster record bull! That clocked in with epic 196.4% gains over 27.8 months without a single 10%+ correction! In raw-price terms, fully 3/7ths of gold's entire bull gains accrued in last year's winter-rally timeframe which accounted for merely 1/7th of its entire duration. Gold's biggest bull ever in dollar terms climaxing is an extreme example, and this year's winter rally won't rival that. But 20%ish gains by late February 2027 wouldn't be much of a stretch. After gold's blowoff top in January, it suffered a necessary severe reckoning plunging 26.3% into mid-July. Then from there gold blasted 17.4% higher into late August, fueled by a huge falling-wedge breakout and Treasury longer-bond buybacks. Had gold entered its winter-rally season there after soaring 17%+ in less than six weeks, its coming outlook would be way less bullish. But from late August to mid-October, gold corrected 12.1% which rebalanced away late August's overextended technicals and bullish sentiment. This latest correction was driven by soaring Fed-rate-hike odds and the resulting strong US-dollar rally, amplifying gold's usual autumn pullback. That dragged gold way back down to just 90.7% of its baseline 200-day moving average last week, not much above mid-July's 88.8% paving the way for August's blistering surge. And that mid-July bottoming proved gold's most-oversold level witnessed in fully 9.6 years relative to its 200dma! Similar levels today also drenched in bearishness provide a low-and-oversold starting point for gold's next winter rally, a great omen. In addition to very-oversold technicals and increasingly-pessimistic herd sentiment, other key factors also argue for a much-stronger-than-usual winter rally this year. Speculators' gold-futures positioning remains quite bullish, with low spec longs giving them huge room to buy and amplify gold upside. Per the latest-available data, total spec longs are running only 23% up into their trading range through gold's late record bull! Gold investment demand also remains robust, with American stock investors just fueling an extraordinary 13-week holdings-build streak in the world-dominant GLD, IAU, and GLDM gold ETFs! Capital continued flowing into gold on balance even despite its recent correction. And both the recent mini-mania in Fed-rate-hike expectations and resulting US-dollar rally are long in the tooth, overdone trades ready to reverse hard. But gold also faces unusual bearish factors due to Trump's foolish war with Iran. That has driven gold's backward war trade this year, selling off on escalations. Traditionally gold surges on geopolitical crises, yet this time resulting higher energy prices stoke inflation fears upping Fed-rate-hike odds which goose the dollar spawning gold-futures selling. Sadly that war and its economic implications look far from over. Another risk is this war's impact on India, the world's third-largest oil importer relying on imports for 7/8ths of its oil demand. Pre-war half of that came from the Persian Gulf. Soaring oil prices hammered India's currency, leading it to more than double import taxes on gold from 6% to 15% in mid-May! After oil, gold is India's biggest import. Higher duties could retard India's gold demand, which is important for gold year-round. Mitigating that risk a bit is India's gold import duties had already long been at 15% prior to July 2024, and that didn't seem to slow Indians' voracious gold consumption. The universal inflation driven by Trump's war could hurt Western holiday jewelry demand too, as higher prices for necessities leave less money left over for discretionary buying including gifts. So this festering war is clouding gold's winter-rally outlook somewhat. Yet even if gold doesn't rally 20%+ by late February, just a 10% winter rally would still be larger than usual. After a quarter-century-plus intensely studying gold and actively trading gold stocks, to me it looks like the bullish factors well outweigh the bearish ones. The major gold miners of GDX tend to amplify material gold moves by 2x to 3x, so even a conservative 10% gold rally could easily push gold stocks 20% to 30% higher. Since GDX was only born in May 2006, it is too young to encompass this secular-seasonality-research thread. So the older HUI NYSE Arca Gold BUGS Index is used instead, which was GDX's predecessor. It still includes most of the same major gold miners at similar weightings, which makes the HUI and GDX functionally-interchangeable. If charted without numeric scales, they'd be indistinguishable from each other. This chart applies this same annual-indexing-averaged-together methodology to the HUI during all these same modern gold-bull years. If GDX was substituted instead starting in 2007, the results would be all but identical. Despite long being ignored by the great majority of speculators and investors, gold stocks have proven one of the best-performing sectors in this past quarter-century. They deserve way more respect.
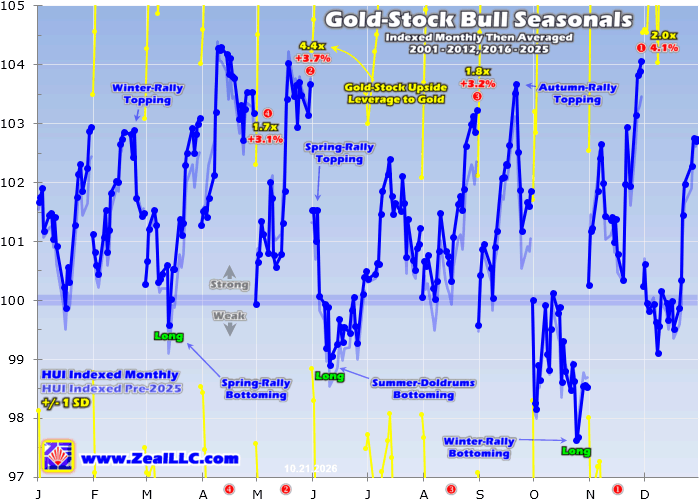
In these same modern gold-bull years of 2001 to 2012 and 2016 to 2025, the major gold stocks averaged phenomenal 27.8% annual gains! That's epic across 22 of these last 25 years, and Wall Street should be crowing about this. Instead this contrarian sector still remains largely ignored. Because of their metal, gold stocks also enjoy distinct autumn, winter, and spring seasonal rallies over the same timeframes as gold. Gold stocks' winter rally is their second-strongest seasonal one of the year averaging 12.0% gains from late October to late February. Yes, gold stocks' autumn-pullback low averages right about now! That argues the recent gold-stock weakness is a good buying opportunity. We've been taking advantage of it to aggressively add fundamentally-superior mid-tier and junior gold-stock trades in our subscription newsletters. During gold's 12.1% correction since late August, GDX has fallen 21.0% at worst as of Wednesday's data cutoff for this essay. That has made for mild 1.7x downside leverage. Because gold's winter rally is so strong, gold stocks' leverage to it has only averaged 1.5x which is the lowest of these three seasonal rallies. Still gold stocks can enjoy some massive gains in this span when gold is really moving, like last year. From late October 2025 to late February 2026, GDX skyrocketed 65.7%! Of course that was driven by gold's late monster record bull going terminal, an extraordinary event. So I certainly don't expect such huge gold-stock gains in this coming winter rally. But again a 20%-to-30% upleg by late February 2027 wouldn't be surprising at all. Like usual gold stocks' coming price fortunes totally depend on how gold fares. Gold stocks are pretty bombed-out today both technically and sentimentally, which really increases the odds for outsized mean-reversion-rebound-and-overshoot gains as gold recovers. When gold runs, gold stocks move fast emerging from oversold conditions and universal bearishness. Despite the apparent lack of interest in this sector, August's example showed investors ready to rush back in when gold is rallying. As gold blasted 17.4% higher from mid-July to late August before traders' Fed-rate-hike paranoia took hold, GDX soared 49.2% in just over five weeks! That made for excellent 2.8x upside leverage, showing investors realize what awesome fundamental bargains gold miners are today. So whenever gold's winter rally starts humming on inevitable speculator gold-futures buying, gold stocks really ought to fly higher again. And that should happen soon, as November has proven gold stocks' strongest month seasonally across all these modern gold-bull years! The HUI averaged hefty 4.1% gains in November, as this chart reveals. Instead of years, it carves gold-stock seasonality into more-granular calendar months using this same indexing-then-averaging methodology. November, December, and January have all averaged quite strong.
Gold stocks' winter-rally months form the largest cluster of seasonal strength through the calendar year. While gold stocks' strong spring rally in April and May is bigger, that's just two months compared to winter's four. From late October to late February is the best time to own gold stocks seasonally, less volatile with good odds of considerable gains. Unfortunately with this sector out of favor, traders have been ignoring it. Multiplying capital in markets requires buying in relatively-low before later selling relatively-high. Yet sadly the tragic paradox of markets is most traders do the opposite. After major selloffs when prices are low which are ideal times to deploy capital, speculators and investors are mostly apathetic or scared and miss these good opportunities. To succeed requires always paying attention, and buying in when you least want to. GDX's 21.0% selloff since late August has been a real grind psychologically, eradicating bullishness and dramatically ramping bearishness in this sector. Maintaining a longer-term perspective looking for trends and reversals in technicals, sentiment, and valuations requires much discipline. It is always hard to follow an out-of-favor sector, and even more challenging to deploy your own capital when few others are willing. Yet that's the only sure way to buy in relatively-low, the necessary prerequisite to later selling relatively-high. Instead most traders ignore battered gold-stock prices after selloffs, then only grow interested and excited well later after they have already soared. Then they chase those gains buying in relatively-high, after the lion's share of those rallies are already over. Later they get gutted in the inevitable subsequent selloffs. Heading into their winter-rally strong season, gold stocks are quite oversold technically, mired in universal herd bearishness sentimentally, and cheap fundamentally. Collectively GDX's component stocks are now trading at an incredible 13.0x trailing-twelve-month price-to-earnings ratio! Gold miners are earning rich-and-fat profits with high prevailing gold, and their stock prices will eventually have to normalize to reflect those. Buying in relatively-low when gold stocks are out of favor is a winning strategy. Over the past quarter-century, our acclaimed subscription newsletters have realized 1,663 stock trades as of the end of Q3'26. Mostly gold and silver miners, their average annualized realized gains including all losers are running +19.9%! That doubles the long-term stock-market average, doubling capital deployed every three to four years! Successful trading demands always staying informed on markets, to understand opportunities as they arise. We can help! For decades we've published popular weekly and monthly newsletters focused on contrarian speculation and investment. They draw on my vast experience, knowledge, wisdom, and ongoing research to explain what's going on in the markets, why, and how to trade them with specific stocks. Our holistic integrated contrarian approach has proven very successful, and you can reap the benefits for only $12 an issue. We extensively research gold and silver miners to find cheap fundamentally-superior mid-tiers and juniors with outsized upside potential. Sign up for free e-mail notifications when we publish new content. Even better, subscribe today to our acclaimed newsletters and start growing smarter and richer! The bottom line is gold and its miners' stocks are entering their winter-rally strong season. This year's ought to prove well above average, since gold just suffered a correction leaving it very oversold and mired in apathy and bearishness. The mini-mania in Fed-rate-hike odds and resulting surging US dollar driving that gold weakness are overdue to reverse, paving the way for sizable-to-large mean-reversion gold buying. Gold-futures speculators are positioned with big capital firepower for buying, which will amplify any gold gains. And American stock investors have been consistently buying for several months even through the recent gold selloff. Once gold decisively reverses and resumes rallying on balance, traders will rush to chase accelerating its upside. And the battered gold stocks will leverage that like usual, surging much higher. ### Oct 23, 2026 Thoughts, comments, or flames? Fire away at zelotes@zealllc.com. Due to my staggering and perpetually increasing e-mail load, I regret that I am not able to respond to comments personally. I will read all messages though and really appreciate your feedback! 321gold Ltd |