|
|||
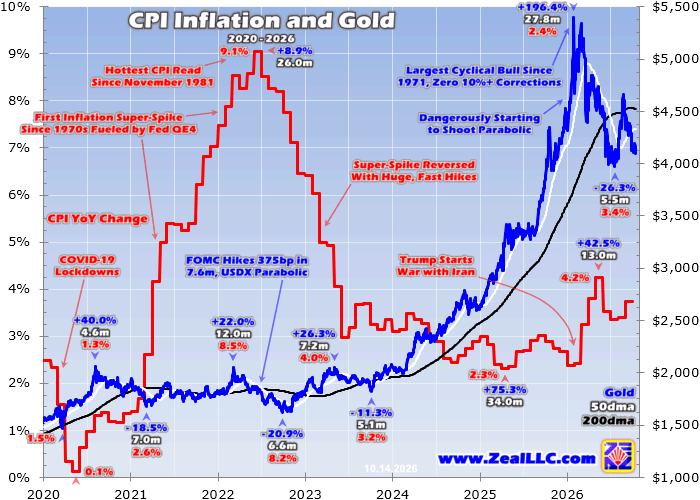
Gold Weathers Warm CPIAdam Hamilton Gold initially sold off fairly sharply following a warmer-than-expected CPI-inflation print midweek. Fearing that significantly boosted Fed-rate-hike odds, gold-futures speculators apparently fled. Yet following that kneejerk reaction, gold recovered some nicely weathering that hawkish data. Regardless of gaming Fed rate trajectories, it is insane traders think higher inflation is bearish for gold given their long historical record. Heading into Wednesday morning's highly-anticipated September Consumer Price Index report, gold was already weak. From late August to early October it had corrected a pretty-big-and-fast 12.0%. The main drivers were soaring Fed-rate-hike odds and the resulting US dollar's blistering rally. Naturally such a large selloff in just six weeks fueled surging herd bearishness. That left gold vulnerable leading into the CPI. Gold was trading near $4,140 in the hours before that data, but rallied near $4,155 just before its release. The headline CPI last month climbed 0.6% month-on-month and 3.7% year-over-year, in line with and 0.1% above economists' consensus. The core version excluding food and energy rose 0.3% and 2.6%, both 0.1% warmer than Wall Street forecasts. The market reaction to that latest inflation data was swift. Futures-implied Fed-rate-hike odds for the FOMC's next meeting in late October soared from 22% to 52% within minutes! The benchmark US Dollar Index blasted up a big-for-it 0.8% to a fresh 18.2-month high! That scared gold-futures speculators into puking out enough contracts to hammer gold down to $4,080 within an hour, a sharp 1.8% intraday plunge. Gold would later close down 1.5% to a new correction low of $4,101. That all seemed overly-dramatic given that CPI's internals. Fully half of that headline jump was driven by surging energy prices due to Trump's war with Iran. The CPI's energy subindex shot up 5.2% MoM and 20.4% YoY, led by gasoline surging 9.1% and 34.2% and diesel skyrocketing 15.3% and 74.2%! Much of that warmer inflation was supply-shock-driven, and Fed rate hikes can't restore global oil and oil-products flows. Trump's war will eventually wind down, and energy shipping out of the Persian Gulf will normalize near pre-war levels. Even if Iran wins control of the Strait of Hormuz, other regional exporters are rushing to construct massive new pipelines to bypass that critical chokepoint. 2026's warmer energy-driven inflation will ultimately prove transitory, and it is not overheating-American-demand-driven subduable by rate hikes. Yet even if this year's inflation surge had been fueled by economy-wide pricing pressures, it is supremely irrational to dump gold futures on it. For centuries if not millennia, gold has been the ultimate inflation hedge. The global aboveground gold supply only grows about 1% annually through mining, vastly slower than fiat-currency growth rates which fuel true debasement inflation. So gold prices rise with general prices. Historical examples are legion, led by the most famous one in the 1970s. During that decade, there were two super-spikes in CPI inflation. From June 1972 to December 1974, the YoY CPI change soared from +2.7% to +12.3%! During that huge 4.6x jump across 30.0 months, monthly-average gold blasted 196.6% higher. And that was only the opening act of that decade's inflation super-spikes, with a bigger one to follow. From November 1976's +4.9% YoY CPI trough to March 1980's soul-crushing +14.8% YoY peak, that leading inflation gauge tripled up 3.0x in 40.0 months. Monthly-average gold skyrocketed 322.4% in that span! More impressively, both of those inflation super-spikes coincided with unbelievably-big-and-violent Fed-rate-hike cycles. During gold's second 1970s bull, the Fed hiked 32 separate times for 1,075 basis points! So gold-futures speculators' belief today that inflation and resulting Fed rate hikes are bearish for gold is absurd fundamentally and historically. Dollar gold's history effectively began in mid-August 1971, when the dollar's peg to gold was severed. Since then the Fed has executed fully 13 rate-hike cycles, defined as 3+ consecutive hikes with no intervening cuts. If they were a threat to gold, 55.8 years of data would prove it. Yet through the exact spans of all 13 of those rate-hike cycles in the dollar-gold era, gold averaged big 26.3% absolute gains! In the majority 8 of those where gold rallied, it clocked in with colossal average 48.4% gains! And during the other 5 were gold fell, its average losses proved asymmetrically-small at just 9.0%. During the last 4 rate-hike cycles since mid-1999, gold averaged excellent 18.7% gains in them! Thus gold's kneejerk selloffs on Fed-rate-hike fears after warmer-than-expected inflation data or better-than-expected jobs data are ridiculous. Given the extreme risks gold-futures speculators run due to the extreme leverage inherent in that realm, it is mindboggling those guys haven't done their homework on gold's historical performance in warmer-inflation and rate-hike periods. They should be rushing to buy. In my line of work as a professional speculator and financial-newsletter writer for over a quarter-century now, I'm blessed to watch the markets all day everyday. I never miss a major-economic-data release and the resulting market reactions and mainstream-financial-news commentary. Listening to the breathless CNBC coverage live after Wednesday's CPI print, you'd think that +3.7% YoY headline bordered on shocking. But it is certainly no dire outlier even in recent context. This chart overlays gold and its key technicals on the headline CPI's annual change since 2020. Gold mostly rallied through the first inflation super-spike since the 1970s following extreme Fed-money printing and government spending after the COVID-19 lockdowns. And CPI inflation was running considerably hotter due to Trump's war earlier this very year.
Inflation sucks, an insidious stealth tax imposed on Americans by endless reckless profligacy from both the Fed and US Treasury. All Americans are suffering from festering inflation's dreadful and wearying bite, especially those responsible for others leading households or businesses. Relentlessly-rising prices are painfully evident every time we buy anything to provide for our families or pay our people. Inflation is miserable. But the markets' reaction fueled by professional traders gaming September's fairly-mild CPI print was way overdone and theatrical. That 3.7% headline CPI merely proved a 4.0-month high, May 2026's +4.2% on Trump's Iran war was much hotter. And right after that supply-shock-driven mini-spike, disinflation quickly returned. Over the subsequent couple months the headline CPI moderated to +3.5% then +3.4% YoY. So far in 2026 despite Trump's war, the monthly headline CPI has averaged 3.3% YoY gains. That's not much higher than 2025's 2.7% and 2024's 3.0%. As far as the FOMC's oft-touted 2% inflation target goes, the CPI hasn't printed at or under that a single time since way back in the year after early 2020's COVID-19 lockdowns! So it's sure not like Wednesday's 3.7% erupted out of super-low inflation leading into it. Inflation data didn't play any role in gold's late monster record bull, soaring 196.4% over 27.8 months into late January 2026 without a single 10%+ correction! Headline CPI inflation was running 3.2% annually when that was born, and 2.4% when it gave up its ghost. From the latest CPI trough of 2.3% in April 2025 to May 2026's peak of 4.2%, in monthly-average-price terms gold surged 42.5% over those 13.0 months. The CPI's big swing prior to that was collapsing from June 2022 super-spike highs of the headline CPI up a terrible 9.1% YoY to April 2025's 2.3%. Monthly-average gold prices soared 75.3% over that long 34.0-month span. From May 2020's deep 0.1% CPI low after the lockdowns crushed the US economy to that June 2022 9.1% CPI peak, average gold climbed 8.9% over 26.0 months. Inflation hasn't governed gold prices. In recent years gold has rallied on balance when inflation skyrocketed, kept rallying on balance through its subsequent collapse, and rallied on balance more as it flared back up thanks to Trump's war. So it's supremely illogical for gold-futures speculators to think warmer inflation is suddenly going to crush gold. Gold's major uplegs and corrections and bulls and bears are mostly driven by global investment demand. Yet in specs' defense, there was one modern episode where Fed rate hikes did hammer gold. But it was so rare and crazy-extreme that there's zero parallel with today. Naturally as that first inflation super-spike since the 1970s mounted in early 2022, top Fed officials freaked out. They were desperate to stuff that inflationary genie back in the bottle. So they embarked on their biggest and most-violent rate hikes in decades. That included four monster 75bp rate hikes in a row! The initial one proved the biggest the FOMC had done since November 1994! Over just 7.6 months in mid-2022, the FOMC hiked an extraordinary 375bp! That's the equivalent of fully 15 individual 25bp hikes, compressed into an incredibly-tight time horizon. Such crazy-aggressive hiking launched the US Dollar Index stratospheric, which hammered gold proportionally. In just 6.0 months into late September 2022, the USDX skyrocketed an epic 16.7% to an extreme 20.4-year secular high! That fueled withering gold-futures selling and investor dumping which crushed gold 20.9% lower in a mostly-parallel 6.6-month span. So perhaps gold-futures specs remember that 2022 episode when they are wildly overreacting to warmer inflation prints. But today is nothing like those extremes. In mid-September 2026, the FOMC hiked 25bp for the first time in 3.1 years in response to war-supply-shock-driven warmer inflation. To qualify as a hiking cycle, the Fed has to hike two more times with no intervening cuts. Even after this week's warmer CPI, that isn't expected to happen before early 2027 at best. There's a decent chance the FOMC won't even get to three hikes, especially if Trump's war wanes. But even if Iran's endless drones and missiles impair ship traffic through the Strait for another few years before new pipelines are built, there isn't a snowball's chance in hell the Fed will hike anything like it did in that extreme 2022 cycle! No matter what happens, we aren't going to see 300bp+ of rate hikes even over a long period of time. So the USDX isn't going to shoot parabolic again, and gold isn't likely to plummet again. Leading into that extreme mid-2022 rate-hike cycle, gold had just regained a 19.0-month high. It was also on the overbought side, stretched 13.1% above its baseline 200-day moving average. In contrast before the Fed's latest hike a month ago, gold had just suffered a serious 26.3% drawdown compressed into only 5.5 months after its late monster record bull. That forced gold 11.2% under its 200dma, for a 9.6-year low! Gold had already recently been slammed to its most-oversold levels in nearly a decade before this latest Fed rate hike. After just having a major selloff, another one isn't in the cards for a few 25bp rate hikes. And if the FOMC indeed hikes again soon as traders expect, it won't be until early December. There's no way top Fed officials will risk hiking at the FOMC's next meeting in late October just days before midterm elections. So maybe the Fed will do two 25bp hikes spread across three months, which is about as mild of hiking as possible. Gold ought to laugh at that. And much can happen in key economic data, markets, and Trump's war between now and early December. So the futures-implied federal-funds-rate trajectory could change considerably. The Fed hiking two more times making for a rate-hike cycle certainly isn't guaranteed. Gold weathered this week's warmer CPI pretty nicely, just as it should have. Gold's recent correction on soaring Fed-rate-hike odds and the resulting much-stronger US dollar has coincided with its usual autumn pullback. Gold's major seasonal winter rally should soon be underway, the strongest of the year. So the recent weakness in gold and especially its miners' stocks look like good buying opportunities before big gains. So we've been aggressively adding fundamentally-superior smaller-gold-miner trades in our subscription newsletters over the past month or so. In addition to excellent production-growth outlooks on new mine-builds and expansions coming online, their valuations remain quite low. The gold stocks will soar again during gold's next major upleg, which should soon gather steam. Now's the time to buy in relatively-low. Successful trading demands always staying informed on markets, to understand opportunities as they arise. We can help! For decades we've published popular weekly and monthly newsletters focused on contrarian speculation and investment. They draw on my vast experience, knowledge, wisdom, and ongoing research to explain what's going on in the markets, why, and how to trade them with specific stocks. Our holistic integrated contrarian approach has proven very successful, and you can reap the benefits for only $12 an issue. We extensively research gold and silver miners to find cheap fundamentally-superior mid-tiers and juniors with outsized upside potential. Sign up for free e-mail notifications when we publish new content. Even better, subscribe today to our acclaimed newsletters and start growing smarter and richer! The bottom line is gold nicely weathered this latest warm CPI inflation. Despite a kneejerk initial selloff on surging Fed-rate-hike odds, gold soon started recovering barely deepening its recent correction. Contrary to gold-futures speculators' irrational bearish reactions to Fed-hawkish economic data, higher inflation is bullish for gold investment demand. Gold's legendary bulls in the 1970s were fueled by inflation super-spikes. In recent years gold rallied through the first inflation super-spike since then, and mostly soared since it collapsed. Gold did get slammed in 2022 on one of the biggest and most-violent Fed-rate-hike cycles ever. But today's situation is radically different, with the FOMC merely likely to gradually hike a handful of times at most. So any gold weakness on warmer-inflation data can be used to boost gold and gold-stock allocations. ### Oct 16, 2026 Thoughts, comments, or flames? Fire away at zelotes@zealllc.com. Due to my staggering and perpetually increasing e-mail load, I regret that I am not able to respond to comments personally. I will read all messages though and really appreciate your feedback! 321gold Ltd |