|
|||
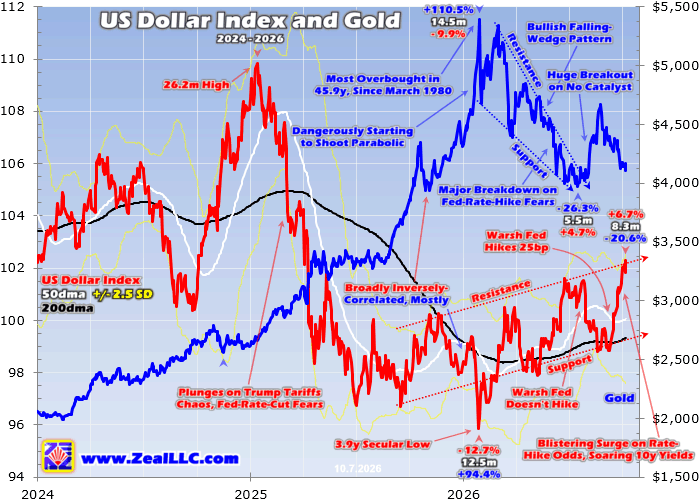
Dollar Hindering GoldAdam Hamilton Despite bullish stars aligning for gold, it has sold off on balance for six weeks now. A sharp reversal from August's blistering rally, this correction has shifted sentiment quite bearish. Surging Fed-rate-hike odds and longer-bond yields have really weighed on gold. Both fueled the US dollar blasting higher since late August, mostly driving gold's selloff since. But the dollar hindering gold is increasingly looking long in the tooth. Gold has long been broadly inversely correlated with the benchmark US Dollar Index. That's logical, as gold has always been universally accepted as money worldwide. So gold's dollar price is effectively its exchange rate. Generally a stronger dollar buys more gold lowering its price, and a weaker dollar buys less gold raising its price. So the US dollar ripping higher since late August has forced down gold prices. Back in mid-July, gold plunged as low as $3,973 on close wrapping up a serious 26.3% drawdown over 5.5 months. That was necessary and healthy after gold's largest cyclical bull ever in US-dollar terms, a 196.4% monster over 27.8 months into late January without a single 10%+ correction! That climaxed at the most-overbought levels gold had witnessed in an eye-popping 45.9 years, since way back in March 1980! During that reckoning, gold carved a massive bullish falling-wedge chart pattern. That matured in early August, igniting a huge gold breakout on no other catalyst. That was soon followed by the US Treasury surprising by upping its buybacks of longer-term Treasuries, accelerating and extending gold's breakneck rally. So by late August, gold had blasted up 17.4% to $4,666 in less than six weeks challenging new-bull territory! The day of that Treasury announcement, the USDX plunged a big-for-it 0.9% to 98.8. Traders seemed to view that new expanded longer-bond buying as quantitative-easing-adjacent, as if the Fed was conjuring up new money to monetize Treasuries. The dollar plunging to that 3.2-month low helped ignite a colossal 3.9% gold up day! When gold peaked four trading days later, the USDX was merely 0.1% above that T-day close. While gold likely needed a breather after such a blistering rally, it could've simply consolidated high. But an unusual series of events coalesced to catapult the USDX well higher in the six weeks since. It started just three days after gold's latest interim high. The USDX rally ignited with a 0.5% surge after Trump's new Fed chairman gave a hawkish speech on fighting inflation at the Fed's annual Jackson Hole symposium. Gold plunged 3.1% that day as futures-implied odds for a 25-basis-point rate hike at the FOMC's looming mid-September meeting shot from 35% to 57% on Kevin Warsh's half-hour speech! Then those kept on climbing on major economic data traders perceived as Fed-hawkish, including a monthly US jobs report and both PPI wholesale inflation and CPI consumer inflation. Those odds were running 91% on FOMC Eve! Bullied by bond traders, the Warsh Fed indeed hiked 25bp which was its first hike in 3.1 years. That day the USDX surged another 0.6% but gold proved resilient only falling 0.7%. A week later US 10-year Treasury yields surged to a 19.2-year secular high of 5.10%, helping fuel another 0.6% USDX up day hitting gold 1.7% lower. The USDX surged another 0.5% on October's opening trading day as fund managers chased. Gold countered that one nicely, still rallying 0.6%. Its inverse correlation with the US dollar is broader, not always day-to-day. And it doesn't always hold sway, as gold can surge even with the USDX on sufficient underlying investment demand. Finally this Wednesday, gold plunged another 1.4% to a fresh correction low of $4,107 as the USDX rallied 0.4% to an 18.0-month high of 102.3 partially on 5.28% 10-year yields. Since gold's latest interim high in late August, the USDX has enjoyed five bigger up days averaging 0.5% gains. Gold averaged 1.3% drops on those same five days. The net result was a big-for-it 3.4% USDX surge over these last six weeks, which forced gold 12.0% lower into formal correction territory. The dollar-gold inverse correlation is highest when gold investment demand isn't strong, due to gold-futures trading. The extreme risks inherent in gold-futures trading demand those speculators play on ultra-short-term time horizons. Midweek each 100-ounce gold-futures contract controlling $410,690 worth of the metal merely required traders maintain margin cash of $20,677 in their accounts. That enables maximum leverage up to 19.9x, which is actually on the lower side of gold futures' usual 20x-to-25x range yet still crazy-risky! At 20x leverage, a 5% gold move against specs' bets would wipe out 100% of their capital risked. So for example on Warsh's hawkish Jackson Hole speech, gold's 3.1% plunge would've multiplied to wild 62.0% losses that day alone! Specs can't afford to be wrong for long in gold futures, or risk fast ruin. They closely watch the US dollar's fortunes, which their trading has turned into gold's dominant short-term driver. That's why gold moves big after major economic data traders think will shift the likely future federal-funds-rate trajectory. Better-than-expected monthly jobs or hotter-than-expected inflation boost Fed-rate-hike odds or reduce Fed-rate-cut odds. That drives the US dollar higher on prospects for higher yields ahead. Gold-futures speculators respond to that dollar strength by selling, which forces gold lower in amplified terms. At 20x leverage, each dollar traded in gold futures has 20x the price impact on gold as a dollar invested outright! So specs punch way above their weights in bullying around short-term gold prices. As this chart of gold overlaid on the US Dollar Index and its key technicals shows, 2026 has seen a strong inverse correlation. If either series was flipped upside down and its axis hidden, they'd be almost interchangeable.
In late January 2026, gold's late monster record bull crested just two days after the USDX fell to a deep 3.9-year secular low. Gold sure needed a reckoning after such an enormous and long-lived bull run, and it coincided with the dollar bouncing and forming a modest new uptrend. That gold drawdown ended as the USDX challenged upper resistance in late June and July, before reversing hard back down to support. The catalyst for that was the Warsh Fed not hiking rates at its late-July FOMC meeting. The USDX fell 0.5% that day and a huge-for-it 1.0% the next, driving gold up 0.6% and 1.5% sowing the seeds for the falling-wedge breakout that would soon ignite. Gold blasted higher as long as the USDX was either sliding lower or staying relatively low. Then gold's six-week correction since inversely mirrored the dollar's surge. Speculators' weekly positioning data in gold futures since early August again confirms this link between gold's price action, the dollar's fortunes, and gold-futures trading. Over four consecutive Commitments-of-Traders weeks into late August, specs flooded into futures equivalent to 44.1, 81.3, 18.0, and 65.8 metric tons of gold buying! That combined for 209.3t, the most over four CoT weeks since early November 2023! But in the subsequent five CoT weeks reported by this Wednesday, speculators' gold-futures trading in gold-equivalent terms collapsed to -46.2t, +17.3t, -26.6t, +3.7t, and -37.1t. At worst in four-CoT-week terms that plunged to -51.9t cumulative, specs' biggest selling since late February 2026. All specs care about, probably all they can care about running at such extreme leverage, is what the US Dollar Index is doing. Yet believe it or not that's getting increasingly bullish for gold on multiple fronts. In this chart note the USDX just blasted back up to its uptrend's upper resistance. That zone has held three consecutive times over the past year or so, leading to the dollar soon falling all the way back down to lower support! If the USDX stalls again here, technically-oriented currency traders will likely be quick to sell reversing the dollar again. And the leverage typical in currency markets even dwarfs gold futures', so all those currency traders have to be technicians to survive. In the US 50x leverage in currencies isn't uncommon, and overseas it can run 100x or even 200x! So if the dollar's upside momentum fades and it stalls threatening to soon roll over, those guys have to exit fast or get obliterated. And two key drivers are poised to reverse the dollar's gains. Those are the same ones that fueled its blistering rally since late August, Fed-rate-hike odds and 10-year Treasury yields. Everything in the financial markets psychologically acts like a pendulum, swinging from one extreme to the other. In the past six weeks traders have all jumped on the Fed-rate-hikes and rising-longer-bond-yields bandwagons, overdoing those moves and universally expecting them to persist indefinitely. When sentiment all crowds one side of the boat on anything, it won't be long until some catalyst emerges to reverse it into a mean-reversion and overshoot. For Fed-rate-hike odds falling, it could be weaker major economic data like the latest monthly-jobs miss or less-hawkish Fedspeak. For 10-year Treasury yields it could be midterm-elections-related, the results implying lower government spending one way or another. As one example, Trump's wildly-unpopular Iran war looks to be all but guaranteeing Democrats win back the House and maybe even control the Senate. Trump has been calling for a 50% increase in US military spending in this new fiscal year to an astounding $1.5t! If Republicans won big, that could be possible. But if Democrats win big, there's not a snowball's chance in hell. There are all kinds of political implications. And it's not just a fading of the recent mini-mania in Fed-rate-hike expectations or surging 10-year yields that could soon push the USDX sharply lower. The US Dollar Index effectively is the euro, as that single currency commands a staggering 57.6% of its total weighting! European debt worries like the current one surrounding France flow and ebb. Remember Greece, Spain, Portugal, and Italy over the past 15 years or so? Midweek the euro closed at a 16.7-month low against the US dollar, so it is as overdone to the downside as the dollar is to the upside. The socialist countries of Europe have always been fiscal disasters, and always will be. Greece, Italy, France, and Spain have debt-to-GDP ratios around 145%, 138%, 117%, and 102% which is scary. But the US's fits right in with those profligates at 127%, leaving the dollar quite euro-like! When the oversubscribed USDX inevitably rolls over again, speculators now have big capital firepower available to flood into gold futures and catapult gold back higher. In the latest-reported data current to September's final Tuesday, speculators' long contracts or upside bets on gold had fallen to just 298.5k contracts. That's the lowest since early August right before gold's huge falling-wedge-breakout surge! And considered in terms of their trading range during gold's late monster record bull from early October 2023 to late January 2026, total spec longs are now merely running 24% up in! So today specs likely have room to quadruple their capital deployed in gold-futures longs, which would drive gold way higher due to leverage's amplified impact on its price. Gold could easily enjoy another August-style surge as the USDX swoons. One more major bullish factor for gold likely to soon stop the dollar hindering it is investment demand. It hasn't been strong in recent months, which is why that inverse dollar-gold correlation held sway as gold-futures trading opposing the dollar's fortunes dominated price action. But American stock investors have been consistently buying despite gold's correction, showing they remain interested in allocating capital to gold. Amazingly for 12 consecutive CoT weeks the combined holdings of the world-dominant American GLD, IAU, and GLDM gold ETFs have enjoyed builds in their bullion holdings! That means their shares are being bought at faster rates than gold, forcing them to add to their physical hoards. There hasn't been a longer streak of major-gold-ETF capital inflows since early 2022, and that one persisted for 13 CoT weeks. Over the past 12 reported CoT weeks, GLD+IAU+GLDM holdings builds have averaged +6.0t weekly. That rivals spec gold-futures trading's +7.4t in gold-equivalent terms. And because of the lag in CoT-week reporting, the last one as of this Tuesday but not yet published also saw a 5.9t GLD+IAU+GLDM holdings build making for the 13th in a row! So American stock investors have remained quite interested in adding gold. When gold reverses hard to surge on big gold-futures buying as the USDX inevitably rolls over, recent simmering investment demand ought to quickly come to a boil. Investors love chasing winners, rushing to deploy capital in fast-rallying assets. So those gold-ETF capital inflows and other investment demand should really accelerate as gold's price action becomes more constructive. That ought to happen any day now. Like usual gold's recent correction has gutted August's increasingly-bullish sentiment, leaving mounting bearishness in its wake. Unfortunately investors and speculators succumbing to that herd groupthink are missing big opportunities. Gold's recent weakness has left it, silver, and their miners' stocks relatively low at good entry prices. So we've been aggressively adding fundamentally-superior smaller-gold-miners trades. Successful trading demands always staying informed on markets, to understand opportunities as they arise. We can help! For decades we've published popular weekly and monthly newsletters focused on contrarian speculation and investment. They draw on my vast experience, knowledge, wisdom, and ongoing research to explain what's going on in the markets, why, and how to trade them with specific stocks. Our holistic integrated contrarian approach has proven very successful, and you can reap the benefits for only $12 an issue. We extensively research gold and silver miners to find cheap fundamentally-superior mid-tiers and juniors with outsized upside potential. Sign up for free e-mail notifications when we publish new content. Even better, subscribe today to our acclaimed newsletters and start growing smarter and richer! The bottom line is gold has been hindered by the surging US dollar for six weeks now, forcing a correction-grade selloff. Currency traders flooded into the US dollar primarily on surging Fed-rate-hike odds and 10-year Treasury yields. But all those swings are way oversubscribed and overdone, ready to mean revert and overshoot the other way. That sets up gold for big gold-futures buying as the dollar rolls over soon. Speculators' gold-futures positioning shows they have massive capital firepower to buy and amplify gold's rally. They could quadruple their upside bets from here based on their trading range during gold's late monster record bull. And American stock investors have continued buying gold ETFs for several months straight despite gold's recent correction. So they should be quick to chase gold rallying again on futures buying. ### Oct 09, 2026 Thoughts, comments, or flames? Fire away at zelotes@zealllc.com. Due to my staggering and perpetually increasing e-mail load, I regret that I am not able to respond to comments personally. I will read all messages though and really appreciate your feedback! 321gold Ltd |